

MoodWallet: Money Management

- 41.00 Reviews
- 4.3
- Downloads
- 10,000+
Our take on MoodWallet: Money Management from Appgk
I approached MoodWallet: Money Management as a finance app for people who want to feel more in control of spending without turning every purchase into a spreadsheet exercise. Its central idea is appealing: connect money decisions with the way they affect your mood, then use that awareness to make calmer choices. In my experience, that makes it feel quite different from a conventional budgeting tool, especially if detailed categories and rigid monthly targets usually make you want to give up.
The app comes from Jomo Labs and is free to start, with optional in-app purchases ranging from $6.99 to $89.99 per item. It is rated for Everyone, runs on Android 7.0 or later, and the current version is 2.12.0. Its average rating is 4.3 from roughly 150 ratings, while the app has passed 10,000 installs. Those figures suggest a smaller product than the major banking and budgeting names, but also one with a clear enough identity to attract people looking for a gentler way to think about money.
How MoodWallet feels to use in everyday money decisions
Readability and navigation without spreadsheet fatigue
The strongest part of the concept is that it does not begin by asking me to build a perfect financial system. Traditional budgeting apps often expect a long setup: income, recurring bills, categories, limits, accounts, and sometimes detailed transaction rules. That approach can be excellent for someone who wants precise tracking, but it creates a high entry barrier. MoodWallet takes a more reflective route, making the emotional side of spending part of the conversation.
That difference matters for readability. Financial information can be technically simple yet emotionally difficult to process. A screen full of totals may be clear to one person and overwhelming to another. A mood-oriented approach gives the user another way to interpret a purchase: not only “What did this cost?” but also “How did this make me feel?” I found that framing more approachable when I wanted to notice habits rather than immediately correct them.
Best Parts of MoodWallet: Money Management
Things to Keep in Mind About MoodWallet: Money Management
For someone who has never maintained a budget, the no-budgeting-required idea is a useful starting point. You can focus on recognizing patterns before committing to limits. I would recommend beginning with one small routine: open the app after a discretionary purchase and record your honest reaction while it is still fresh. The useful information is often not whether the purchase was objectively good or bad, but whether it brought relief, excitement, guilt, indifference, or regret.
The most practical insight is to treat the app as a decision-awareness tool before treating it as a money-control tool. That change in expectation prevents disappointment. It is not the same as a full accounting package, and it does not need to be. Its value is in helping users pause long enough to notice the connection between spending and emotional state.
News and Features Related to MoodWallet: Money Management

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
Navigation is also easier when I use it for a specific question instead of browsing aimlessly. For example, I might look back at recent spending and ask whether convenience purchases consistently improve my day or merely solve a momentary problem. That kind of focused review is more manageable than trying to understand every aspect of my finances at once.
Motor and sensory considerations in the real world
Finance apps can be demanding for users with different physical or sensory needs because they often rely on small controls, dense figures, and repeated input. MoodWallet’s simpler premise may reduce the amount of information a person has to process at one time, but a less complicated concept does not automatically make every interaction accessible. I would judge the experience by whether the user can comfortably read, select, and reflect on entries on their own device.
Don't want to read the full review?
For users with limited dexterity, the main question is how much repeated tapping or typing the chosen workflow requires. A person who finds long forms tiring may benefit from using the app in short sessions rather than trying to document an entire week. Recording one meaningful purchase at a time is a more realistic habit than promising to reconstruct every transaction later. It also preserves the emotional context that makes the app distinctive.
People with low vision may need to adjust their phone’s display settings or use built-in screen magnification, depending on how comfortably the interface presents text and controls on their device. I would not assume that a finance app’s clean appearance guarantees strong support for every visual need. Before relying on it as a primary money tool, I would test the most important actions: opening an entry, reading the amount or reflection prompt, editing a mistake, and returning to the main view.
Screenshots
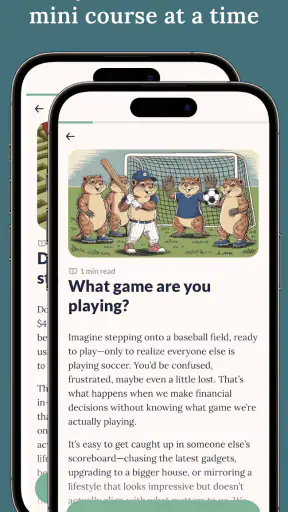
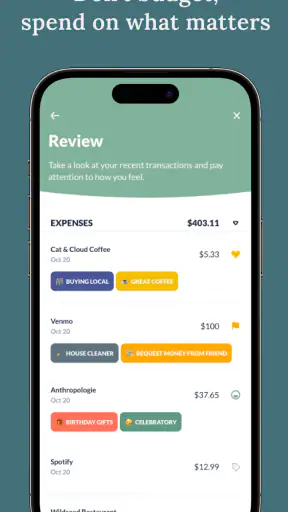
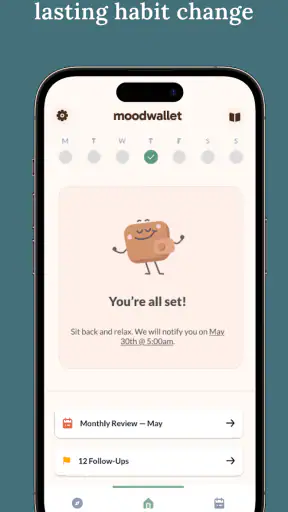
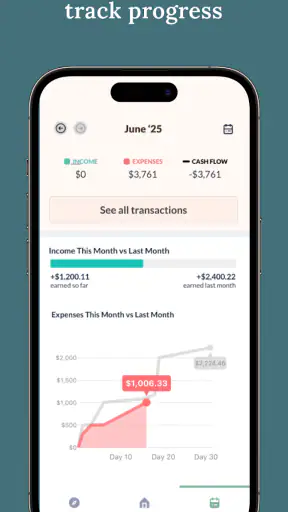
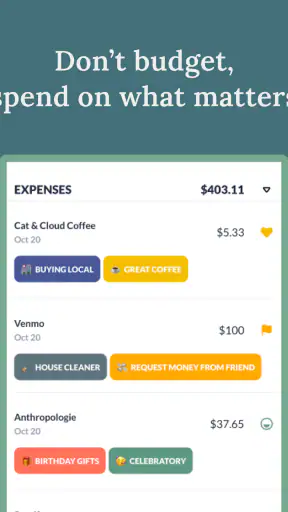
Users with color-vision differences should be cautious about interpreting meaning from color alone. Financial and emotional interfaces sometimes use color to suggest positive or negative states, but a good personal workflow should still make sense through words and numbers. If an item is difficult to distinguish visually, I would record a short written note rather than relying on a visual cue. That also makes later reflection more useful.
For people who process information better in small pieces, the app’s emotional framing can be less intimidating than a large financial dashboard. I would keep sessions deliberately brief and avoid reviewing spending when already stressed. The goal is to create a calm pause, not another task that feels like a test. Someone who prefers audio guidance, keyboard-heavy navigation, or highly configurable presentation should check the experience on their own phone before making it central to their routine.
Situational access: useful when life is already busy
Accessibility is not only about permanent disability. A person may be tired, distracted, anxious, commuting, caring for a child, or trying to make a decision in a noisy shop. MoodWallet makes the most sense in these moments when the user needs a quick mental checkpoint rather than a complete financial report.
Consider a realistic example. I am about to buy an expensive item after a difficult day. A conventional budget might tell me whether the category has room left, but it may not explain why the purchase feels unusually urgent. A brief reflection can expose the real motive: I may be seeking comfort, convenience, recognition, or simply a break from stress. That does not mean the purchase is automatically wrong. It means I can decide with more awareness instead of confusing an emotional need with a financial need.
Another useful situation is after a social event. Group meals, gifts, and spontaneous plans can be difficult to evaluate while they are happening. Later, I can use the app to distinguish spending that genuinely supported relationships from spending accepted only because I felt pressured. That distinction is more nuanced than labeling all social spending as unnecessary.
The app can also suit people whose income or expenses vary and who find fixed monthly budgets unrealistic. A strict limit may create frustration when bills, freelance work, or household needs change. Mood-based reflection does not solve irregular cash flow, but it can still help identify avoidable patterns during uncertain periods. I would pair it with a simple bill calendar or bank review if I needed a dependable view of upcoming obligations.
For users sharing financial responsibilities, the situation is more complicated. A personal reflection tool can help me understand my own choices, but it should not replace a shared method for rent, utilities, debt, or family planning. If several people need the same current figures, a traditional shared budget or account-management solution is likely more suitable. MoodWallet is strongest as an individual layer of awareness, not as a household ledger.
It may also help someone returning to financial organization after burnout. Starting with emotional reactions is less demanding than immediately categorizing every transaction. My suggested workflow would be to use it for a week of observation, identify one recurring trigger, and then choose one small adjustment. For instance, I might delay comfort purchases until the next morning or set aside a specific amount for enjoyable spending. The app becomes a prompt for a behavior experiment rather than a source of guilt.
Where the approach falls short
The same simplicity that makes MoodWallet approachable can limit it for users who need precision. If I want detailed account balances, automatic reconciliation, debt payoff projections, tax records, or a complete transaction history, I would choose a more established budgeting or personal-finance platform. Mood awareness can explain behavior, but it cannot by itself guarantee that bills are covered or that a savings target is on track.
There is also a risk of overinterpreting feelings. A purchase that produces guilt is not necessarily irresponsible, and a purchase that feels good is not necessarily affordable. I would use the app to add context, never as the sole test of whether a decision is financially sound. The best results come from combining emotional notes with basic facts such as available cash, upcoming commitments, and longer-term priorities.
Optional purchases may also affect how comfortable different users feel with the experience. The app is free to start, but the presence of in-app items from $6.99 to $89.99 means I would review any upgrade carefully and decide whether it supports a real habit. A reflective finance tool should not become another source of pressure. If the free experience already helps me notice patterns, I would only pay for something that clearly improves my routine.
New users should also be realistic about consistency. An app cannot reveal useful patterns if I open it only when I feel guilty. That creates a biased record made up of regretted purchases. A better method is to log a mixture of ordinary, positive, and disappointing spending. Comparing those entries produces a fairer picture of what actually improves my life.
The relatively modest community around the app can be a consideration as well. An average rating of 4.3 from around 150 ratings is encouraging, but it does not carry the same breadth of user experience as a finance service used by millions. I would therefore test it personally before moving away from another system that already handles essential records. Its smaller scale is not a flaw by itself, but it is a reason to keep a backup of important financial information elsewhere.
People who need formal accessibility assurances should take an especially careful approach. I would test navigation with the device features I depend on, including larger text, magnification, voice interaction, or alternative input. The app’s friendly purpose is promising, but inclusive design is ultimately judged by whether a particular person can complete important tasks comfortably and independently.
Who should use it, and who should choose another tool?
I would recommend MoodWallet to someone who repeatedly makes spontaneous purchases, feels anxious about budgeting, or wants to understand the emotional triggers behind spending. It is also a good candidate for people who abandon conventional finance apps because setup feels too demanding. The app gives those users a softer entry point: observe first, then decide what deserves a change.
I would be more cautious recommending it to someone managing complex finances. If you have several accounts, shared household obligations, irregular debt payments, business expenses, or strict savings deadlines, you need a system built around accurate records. MoodWallet can complement that system by adding personal reflection, but it should not replace the tool that tells you exactly what is due and when.
It is also not the best match for users who dislike journaling or emotional self-assessment. Some people want a finance app to show a clear number and a direct action. For them, a zero-based budget, expense tracker, or banking dashboard may feel more efficient. MoodWallet asks for a different kind of attention, and that can feel valuable or unnecessary depending on your personality.
My most useful tip is to define the question before opening the app. “Why do I keep making this kind of purchase?” is better than “I need to fix my finances.” The first question is specific enough to answer. Once I identify a pattern, I can make a practical change outside the app, such as adding a waiting period, creating a guilt-free spending allowance, or discussing a recurring expense with someone in the household.
An inclusive verdict for a gentler finance routine
MoodWallet: Money Management stands out because it treats spending as a human behavior rather than only a collection of figures. Developed by Jomo Labs, it offers a free starting point for adults and younger users covered by its Everyone rating, while Android users need version 7.0 or later. Its current release, 2.12.0, gives the app a clear place in the modern finance category without pretending to be a replacement for every financial tool.
I like it most as a low-pressure companion for reflection. It can help me notice whether purchases match my values, whether stress is influencing decisions, and which small changes might make spending feel more intentional. That is especially useful for people who find conventional budgets visually dense, emotionally discouraging, or difficult to maintain.
My recommendation comes with a boundary: use it alongside basic financial safeguards when your situation requires accuracy. Keep essential bills, balances, and deadlines in a dependable system, then use MoodWallet to understand the personal decisions that numbers alone cannot explain. Test the interface with your own accessibility settings, work in short sessions if input is tiring, and avoid treating mood as proof that a purchase was wise or unwise.
For me, its inclusive strength is the invitation to begin without demanding financial perfection. It will not solve every money problem, and users who need advanced tracking should look elsewhere or pair it with another service. But for someone who wants a calmer, more readable path into spending awareness, this finance app offers a thoughtful alternative to the usual budget-first approach.
MoodWallet: Money Management FAQ
What is MoodWallet: Money Management, and who is it designed for?
MoodWallet: Money Management is a personal finance app designed to help users understand and organize their everyday spending. Its focus is not only on recording income and expenses, but also on connecting financial activity with moods and habits. It may be useful for people who want a clearer overview of their budget, identify emotional spending patterns, and build more mindful money-management routines without relying on complicated spreadsheets.
How can MoodWallet help me track my expenses and manage a budget?
The app can be used to record financial transactions, organize spending into categories, and review where money is going over time. By entering purchases consistently, users can compare expenses with their available budget and recognize categories that may need attention. The experience is most effective when information is kept up to date, since the app should be treated as a tracking and planning tool rather than an automatic replacement for checking bank statements.
Does MoodWallet connect directly to my bank account or financial services?
Before downloading, users should check the app’s current feature list and privacy information to confirm whether bank synchronization is available in their country and on their device. Some versions of money-management apps rely on manual transaction entry, while others may support integrations through third-party services. If you prefer not to share financial credentials, manual tracking can offer more control, although it requires additional effort and regular updates.
Is MoodWallet safe to use for personal financial information?
MoodWallet may contain sensitive information such as spending records, budgets, and personal financial notes, so privacy should be considered before use. Review the permissions requested, the developer’s privacy policy, data-storage practices, and whether information is encrypted or shared with third parties. Avoid entering banking passwords, card PINs, or other confidential credentials unless the app clearly explains a secure, reputable connection method.
Is MoodWallet free, and are there any in-app purchases or limitations?
The availability of features, advertising, subscriptions, and in-app purchases can vary between Android and iOS versions and may change after updates. Before installing, review the store listing carefully to see which tools are included at no cost and whether advanced reports, customization, cloud backup, or other options require payment. Checking the subscription terms is especially important if you only want to use the basic budgeting features.











